
Our publications.
Reading material for anyone who wants to know more. You can read our articles and the explanations of individual distributions right here and download further papers from SSRN.
Articles to read.
You can find these articles in full length directly on this website.
 When Do I Use Which Distribution?The guide to the most important distributions, from the occurrence of a risk to its impact.
 How does risk aggregation work under IDW PS 340 and StaRUG?Case study: how to assess risks gross and net, aggregate them into an overall risk with a Monte Carlo simulation and compare them with the risk-bearing capacity, shown with a risk model in Excel.
 How do you assess credit risk from receivables with a Monte Carlo simulation?Case study: how to assess credit risk from receivables with a Monte Carlo simulation, with correlated defaults and debt collection.
 How do you assess cyber risks with a Monte Carlo simulation?Case study: how to break cyber risks down into attack frequency, vulnerability and losses, assess them with a Monte Carlo simulation and combine them into a risk cluster for enterprise risk management.
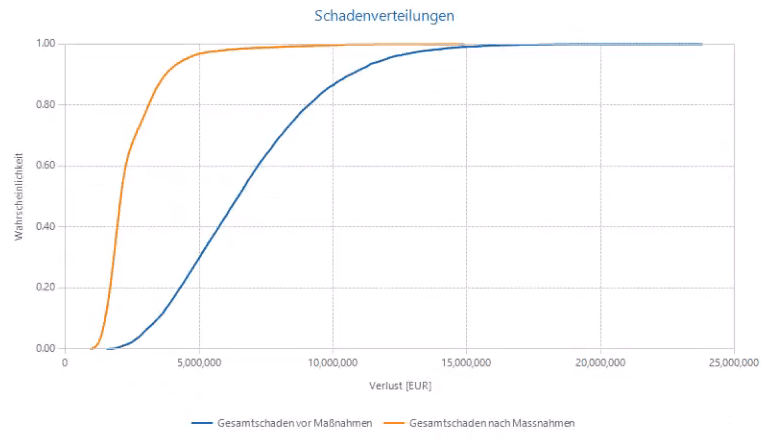 How does risk assessment work in enterprise risk management?Case study: how to assess risks in enterprise risk management with suitable distributions, aggregate them, compare them with the risk-bearing capacity and model them from their drivers.
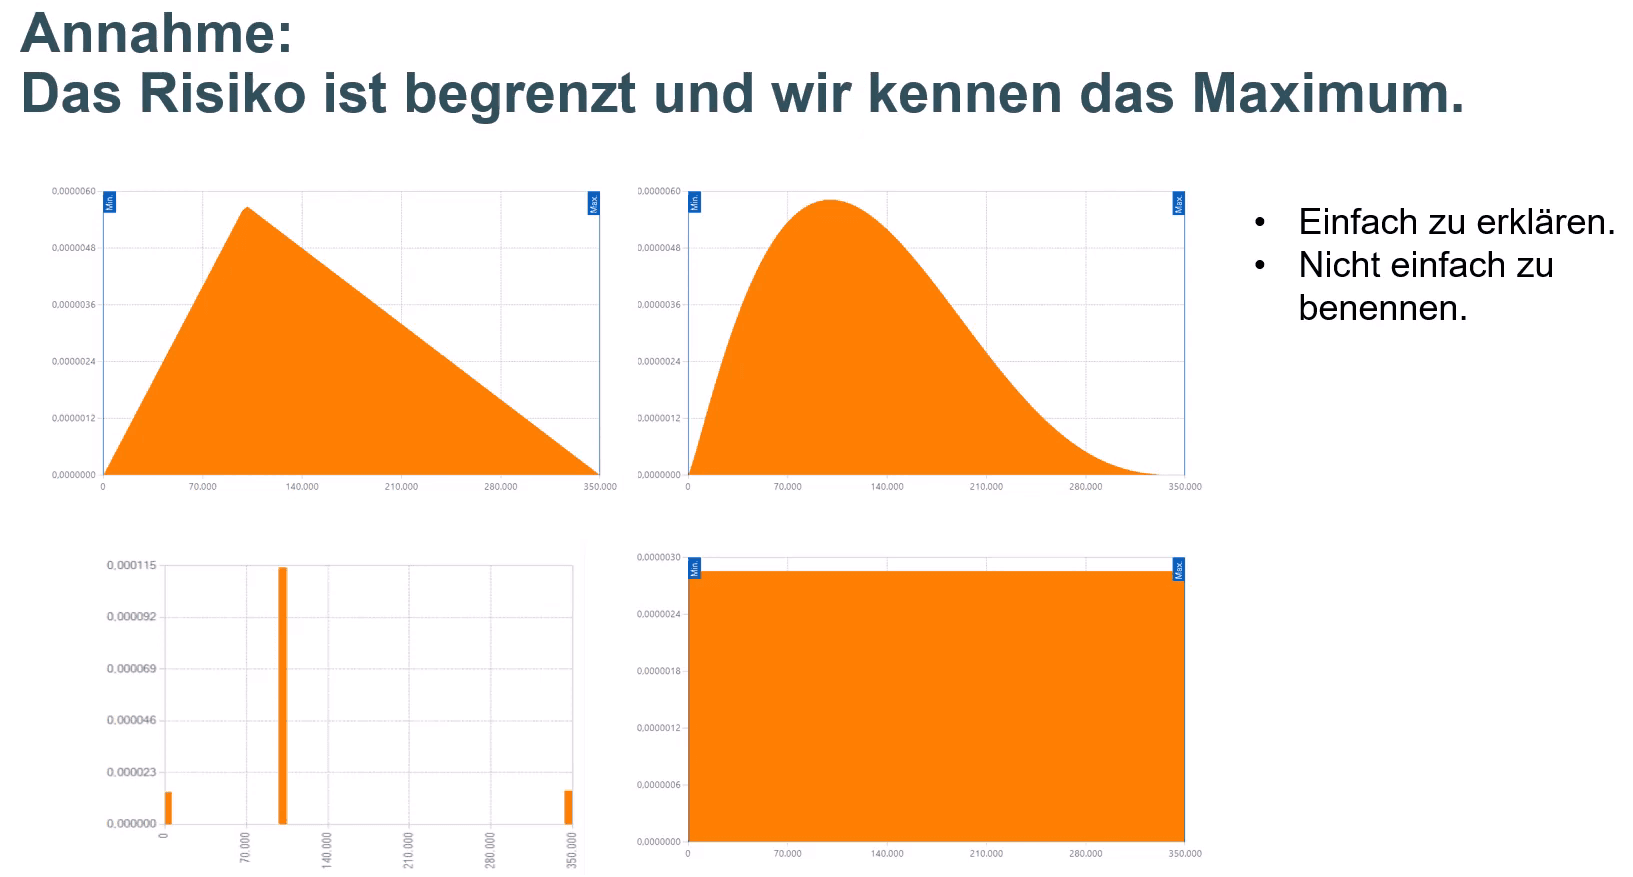 Is exceeding a three-point distribution a black swan?Anyone who assesses risks with a minimum, a most likely value and a maximum silently assumes a known maximum, and it is precisely this assumption that breaks down in severe crises.
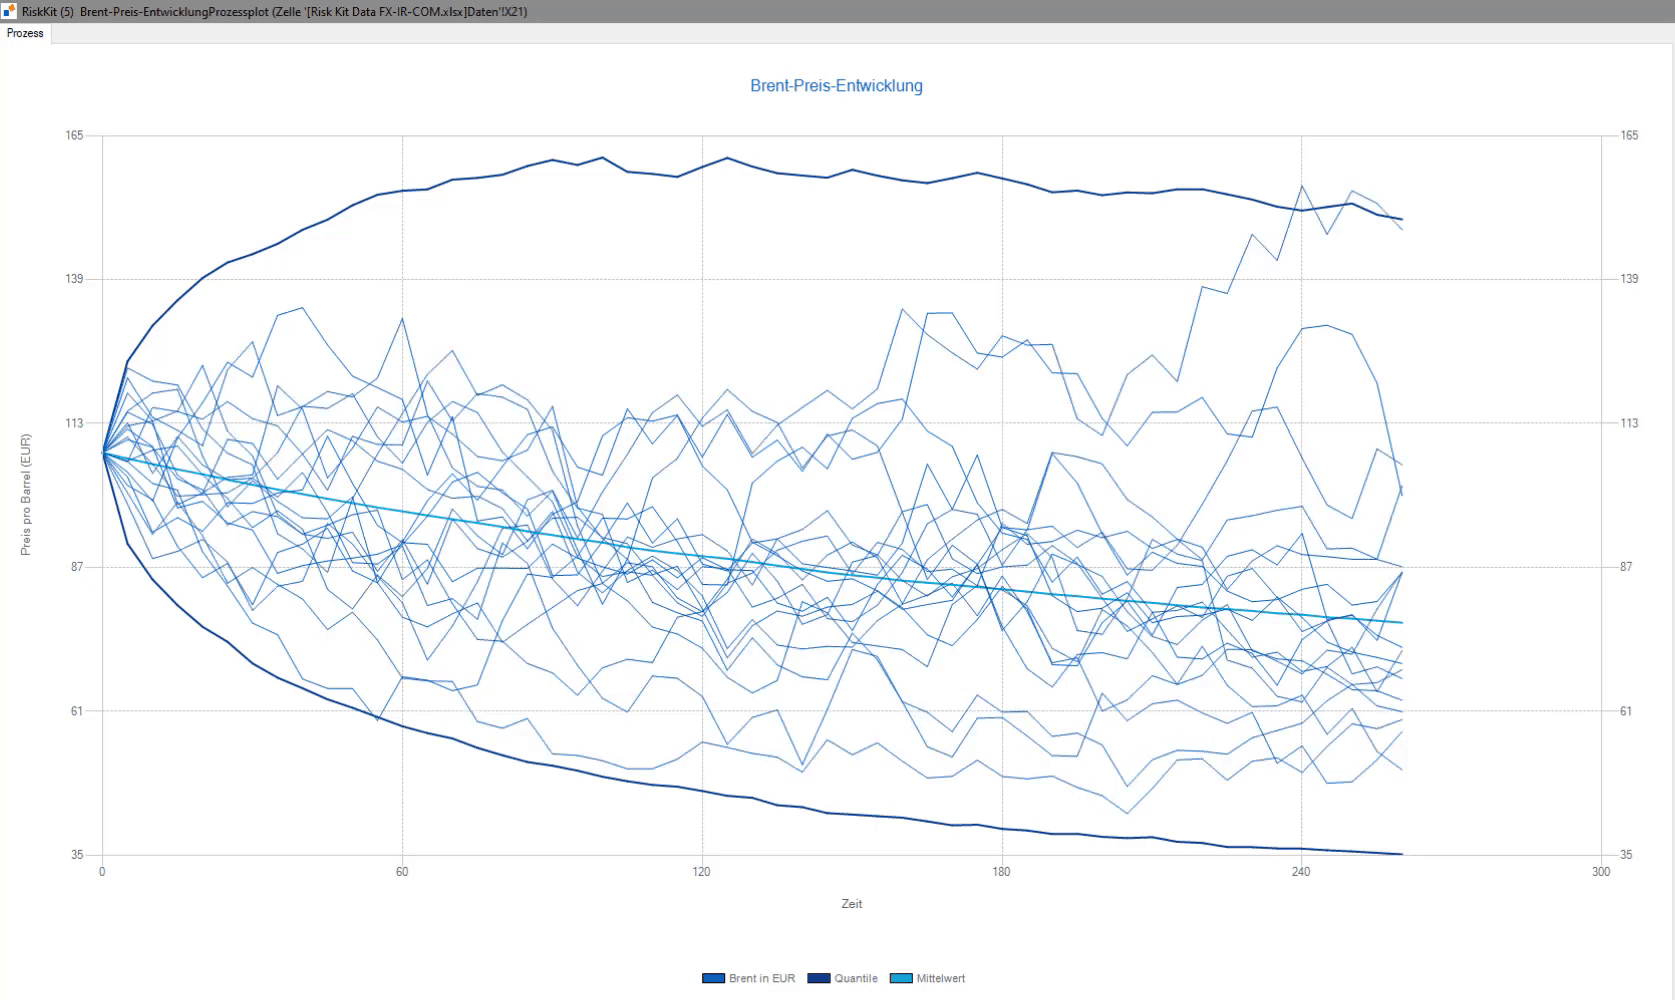 How do you simulate price movements with a Monte Carlo simulation?Case study: how to calibrate the oil price and interest rates to historical data, simulate them as price paths and run scenarios with a trend of your own.
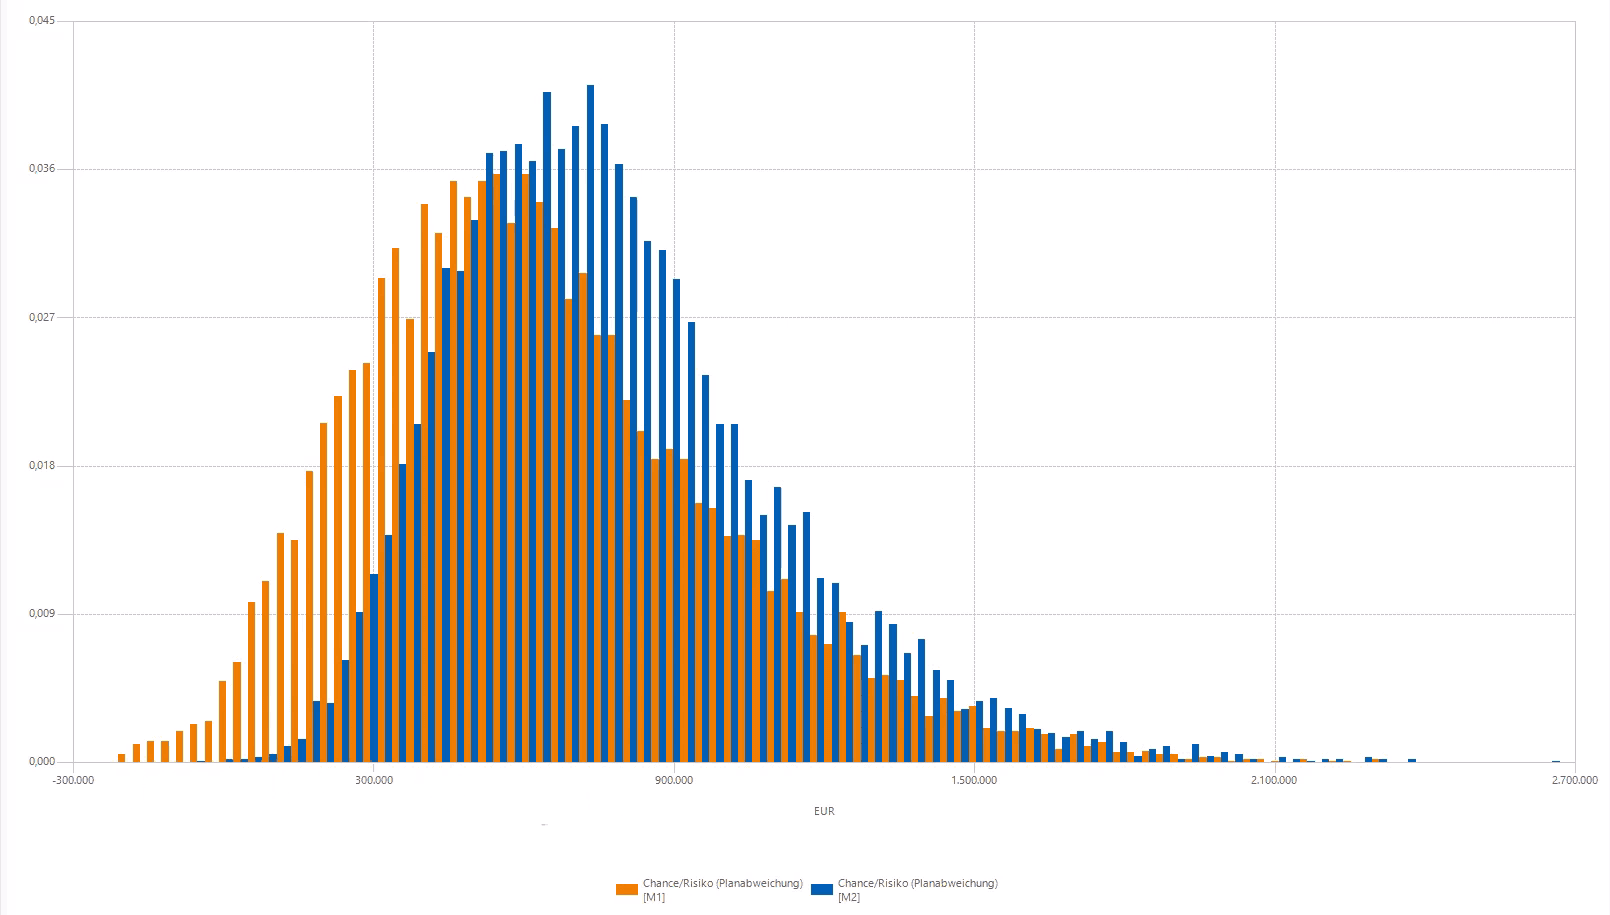 How do you analyse project risks with a Monte Carlo simulation?Case study: how to assess project risks from expert estimates of the tasks with a Monte Carlo simulation, find their drivers and track them as the project progresses.
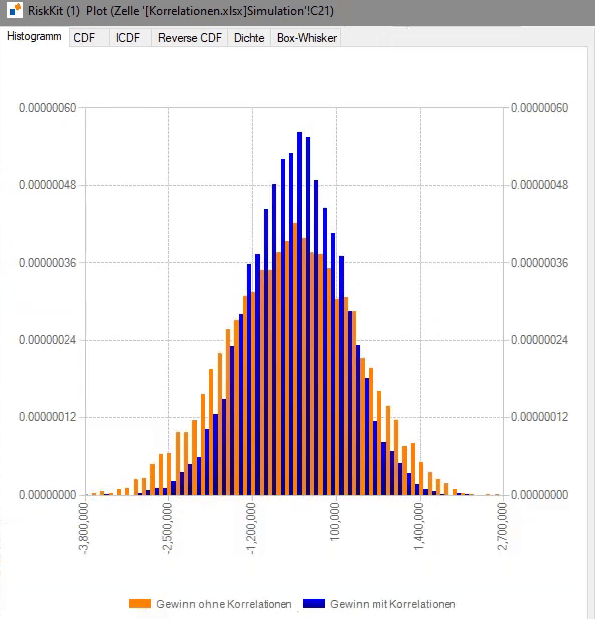 How do you take correlations into account in a Monte Carlo simulation?How to build correlations between risk factors into a Monte Carlo simulation with a copula, why they change the range of the result and how to estimate them from data.
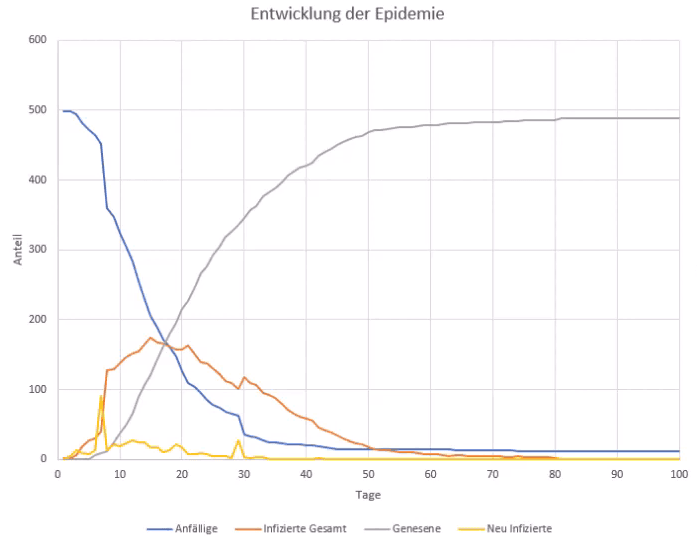 How do you assess the risk of business interruptions from a pandemic with a Monte Carlo simulation?Case study: how to use a Monte Carlo simulation to determine how likely and how long business interruptions from an epidemic are, and what testing, quarantine and other measures achieve.
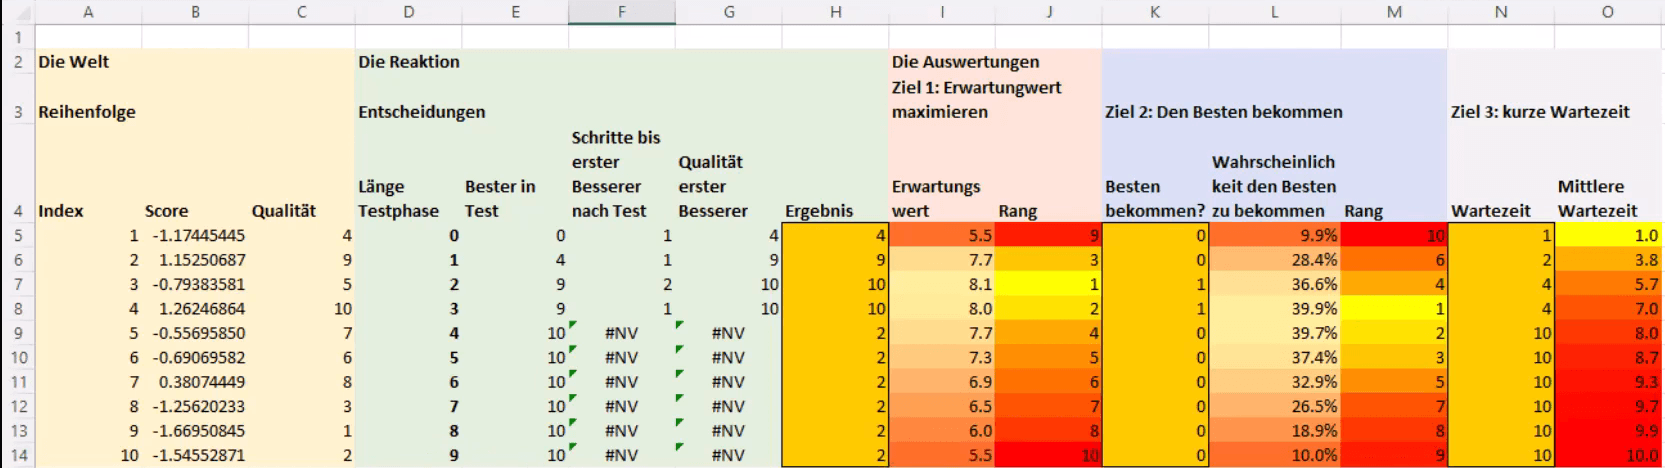 Who should I marry? Selection decisions with Monte Carlo simulationCase study: how to use a Monte Carlo simulation to find out how long to just test candidates before committing.
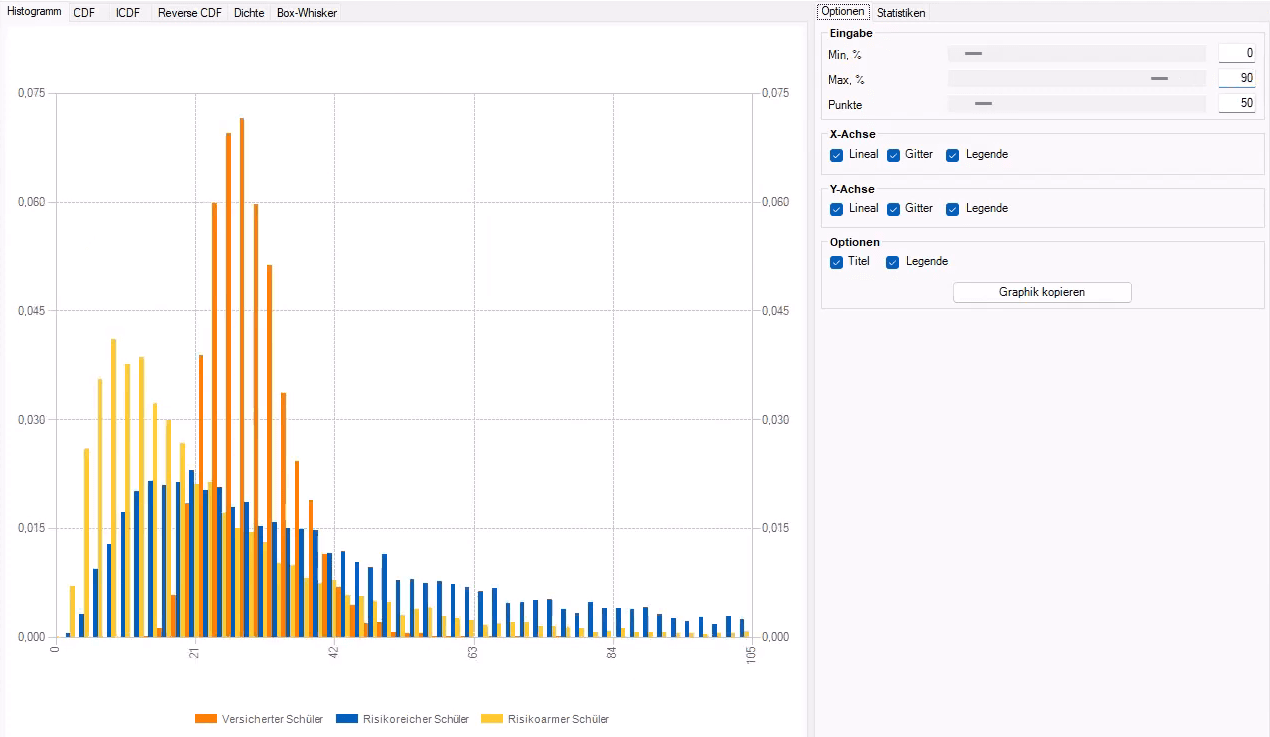 How do you build a Monte Carlo model? Three examples from a school trip to an insurance schemeThree examples from one school class show step by step how to build a Monte Carlo model in Excel, analyse it and derive measures from it.
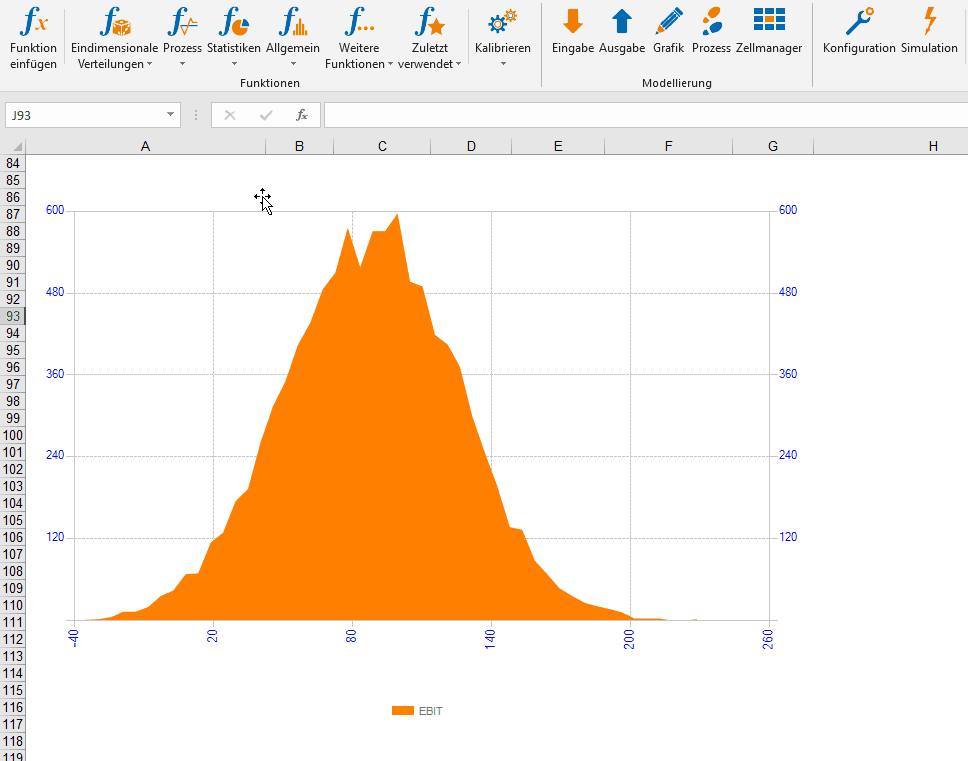 Monte Carlo Simulation with Risk KitThe in-depth tutorial: from your first profit and loss simulation to sensitivities and charts.
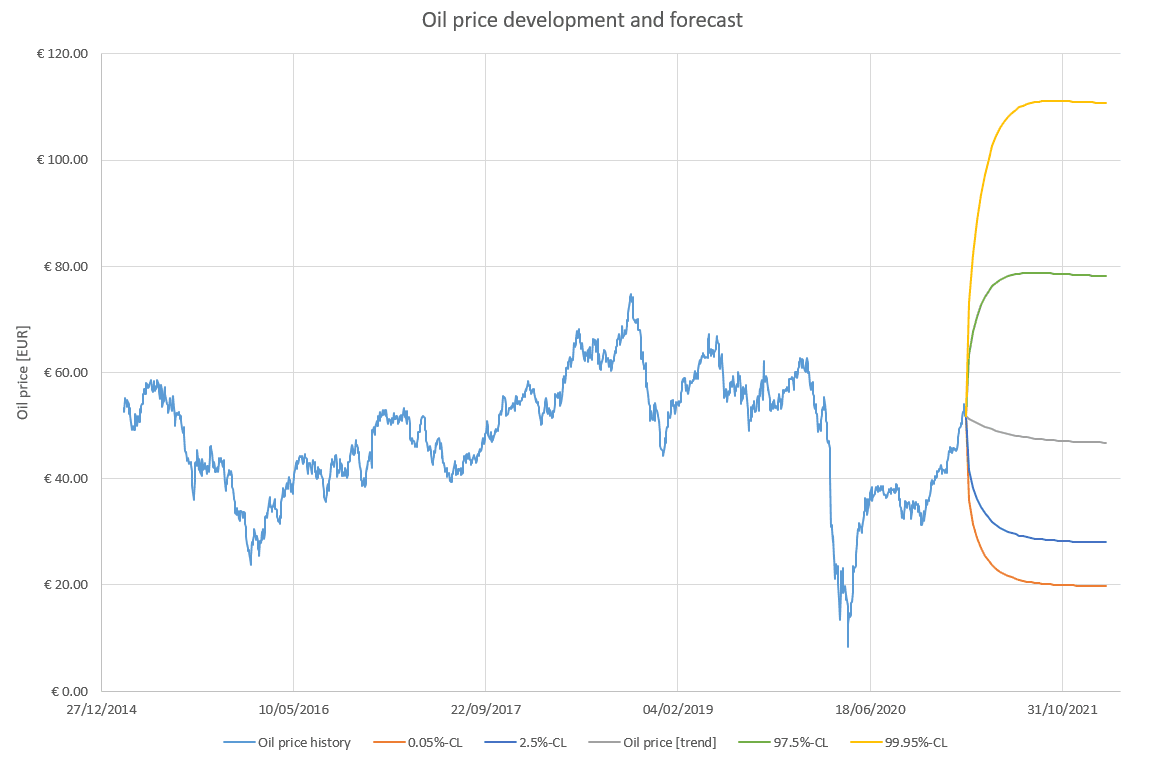 Live Access to Large International Data Sources with Risk Kit DataCase study with Risk Kit Data: how oil prices, foreign exchange rates, and interest rates affect profit and loss.
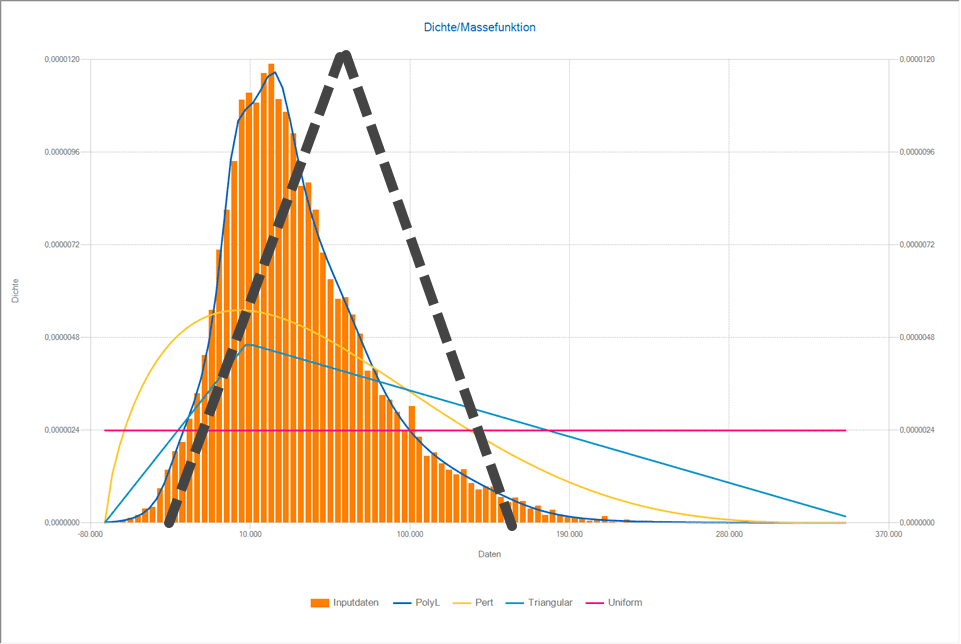 Early Warning Indicators for Problematic Expert AssessmentsHow to recognize problematic expert assessments before they distort risk aggregation.
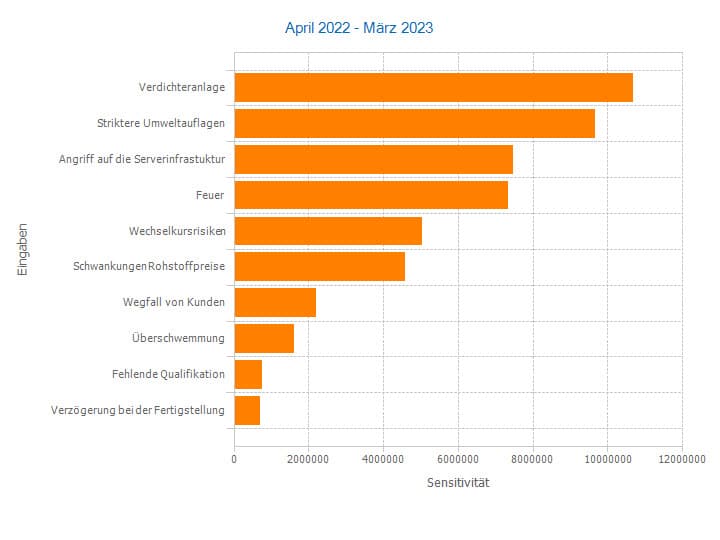 Sensitivities: Finding Problems and Setting PrioritiesHow sensitivities identify the problematic risk drivers and justify priorities for management.
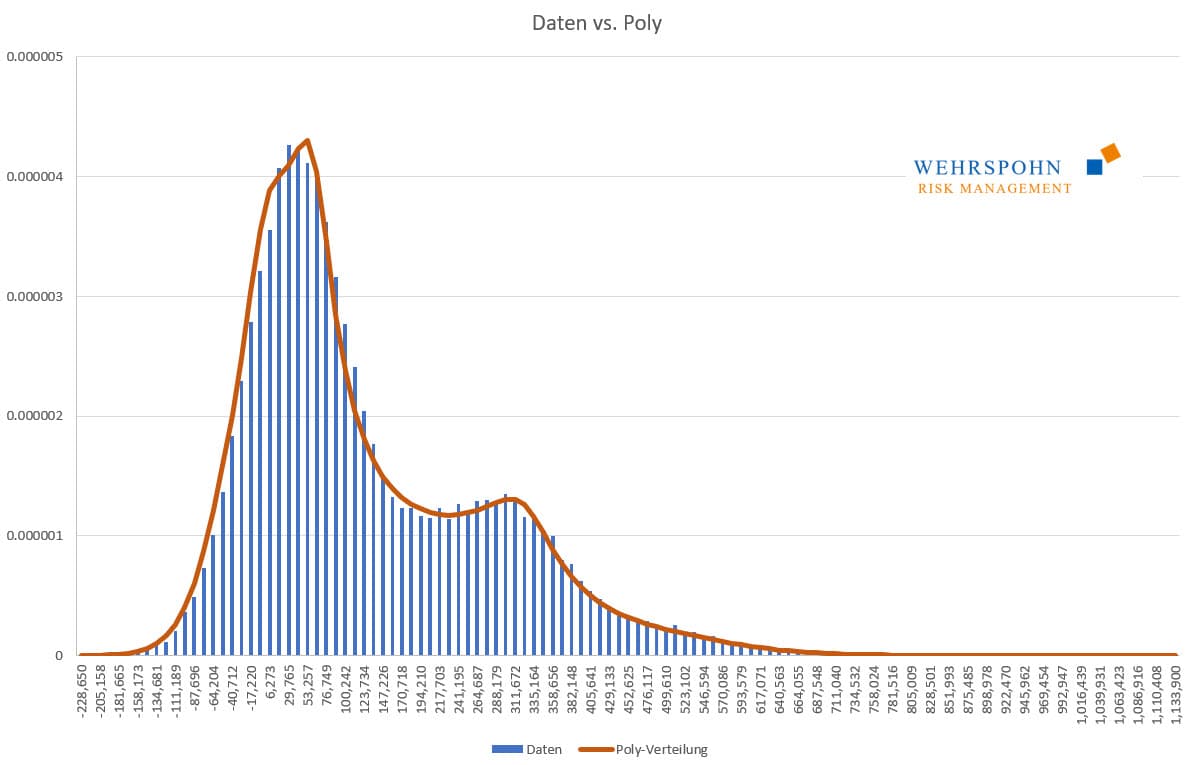 Expert and Poly DistributionsFlexible distribution families that do equal justice to expert assessments and data analyses.
Distributions explained one by one
One article per distribution, based on our video series: what it describes, when to use it and how to simulate it.
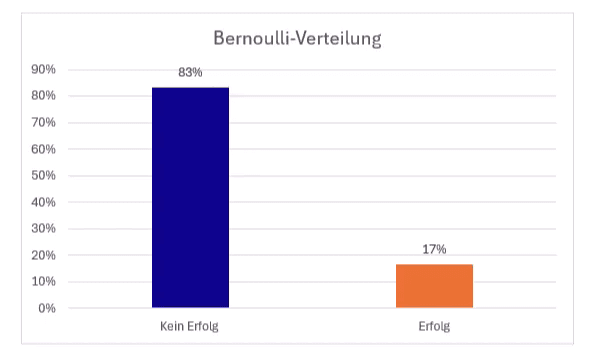 When do I use a Bernoulli distribution in a Monte Carlo simulation?Definition, formula and examples: when the Bernoulli distribution fits and what role it plays as a switch in a simulation.
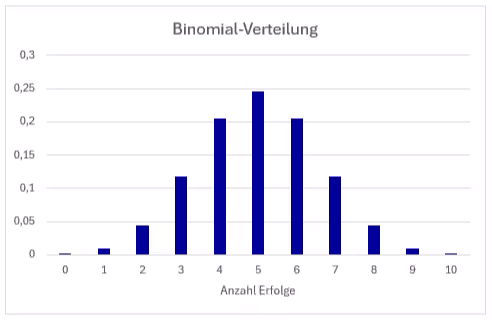 When do I use a binomial distribution in a Monte Carlo simulation?Definition, formula and examples: how the binomial distribution describes the number of successes in n independent trials and how to calculate it in Excel.
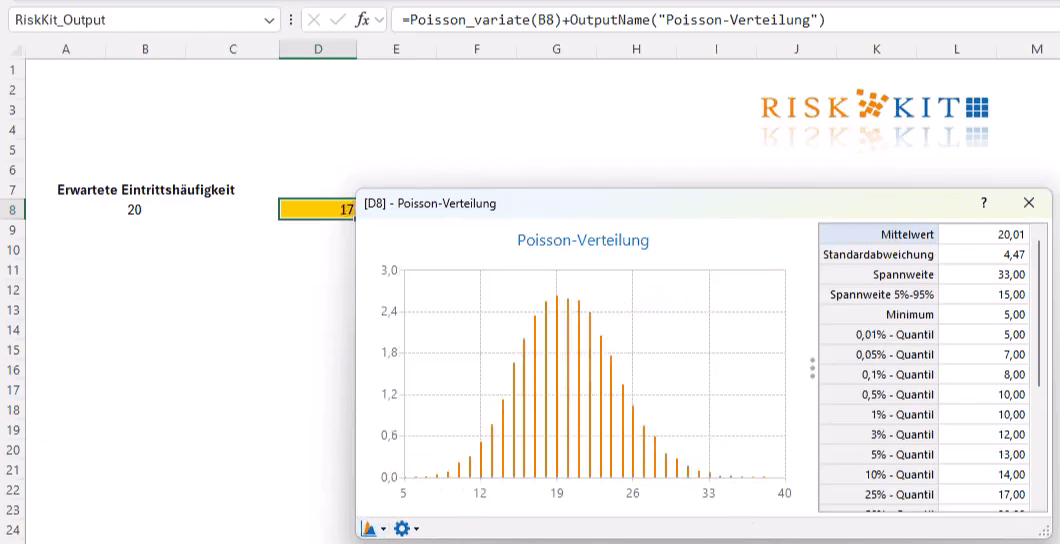 When do I use a Poisson distribution in a Monte Carlo simulation?Definition, formula and examples: how the Poisson distribution describes the frequency of independent events and when it fits.
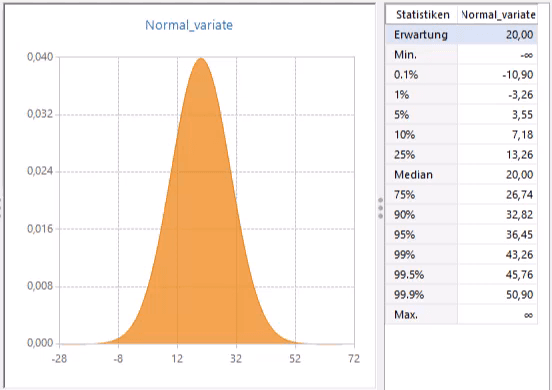 When do I use a normal distribution in a Monte Carlo simulation?Definition, formula and examples: when the normal distribution fits, where its limits lie and how to truncate it.
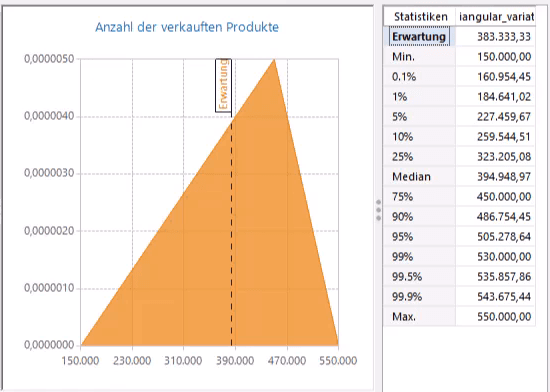 When do I use a triangular distribution in a Monte Carlo simulation?Definition, formula and example: when the triangular distribution fits, why the most likely value is not the expected value and where its limits lie.
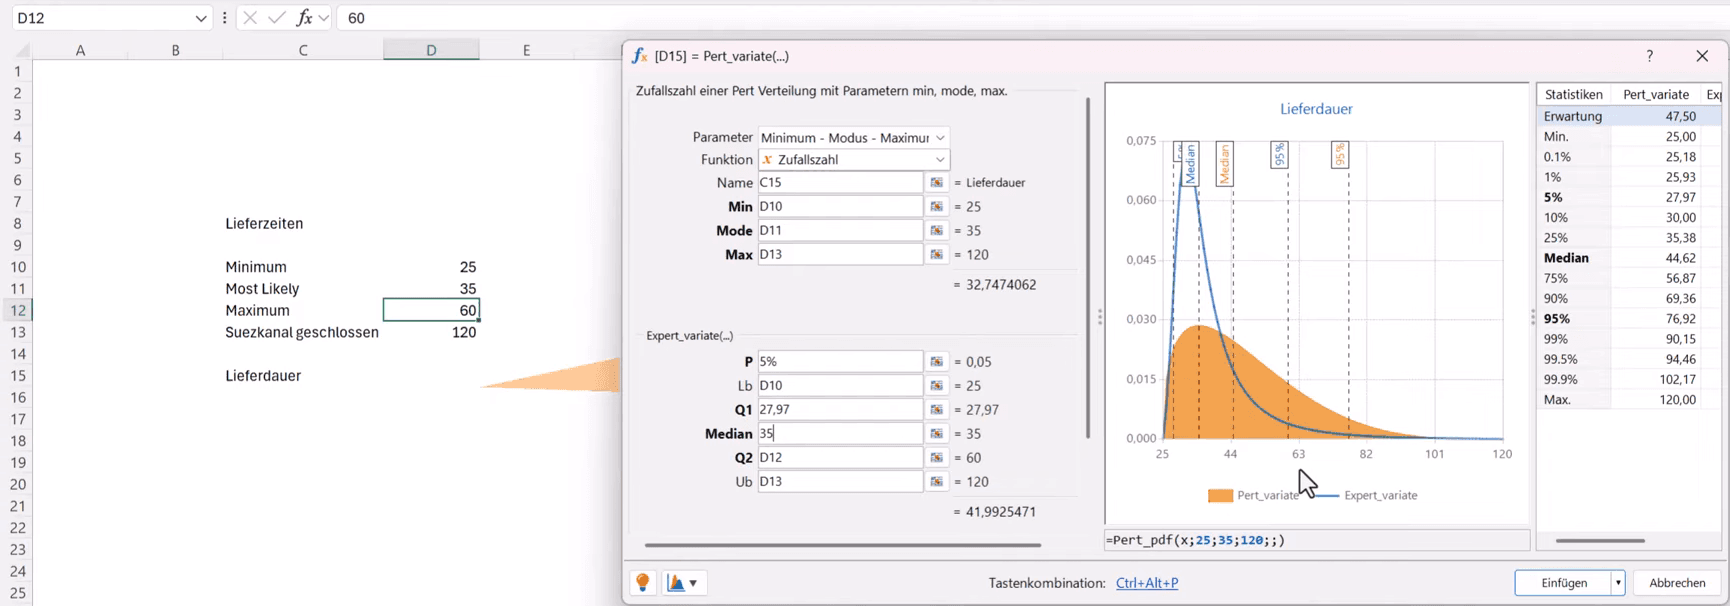 Quantifying expert estimates in a Monte Carlo simulation: the Expert distributionQuantifying expert estimates better: how the Expert distribution captures estimates through bounds and quantiles, even without a fixed minimum or maximum.
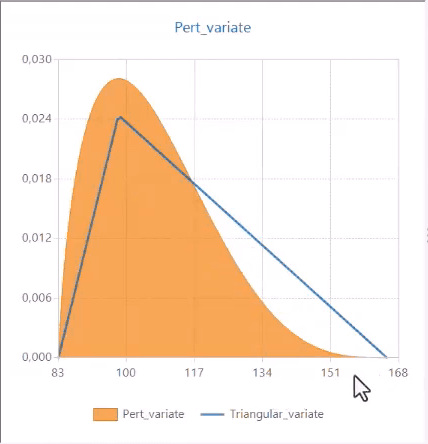 When do I use a PERT distribution in a Monte Carlo simulation?Definition, formula and example: how the PERT distribution describes a bounded duration with minimum, most likely value and maximum, and where its limits lie.
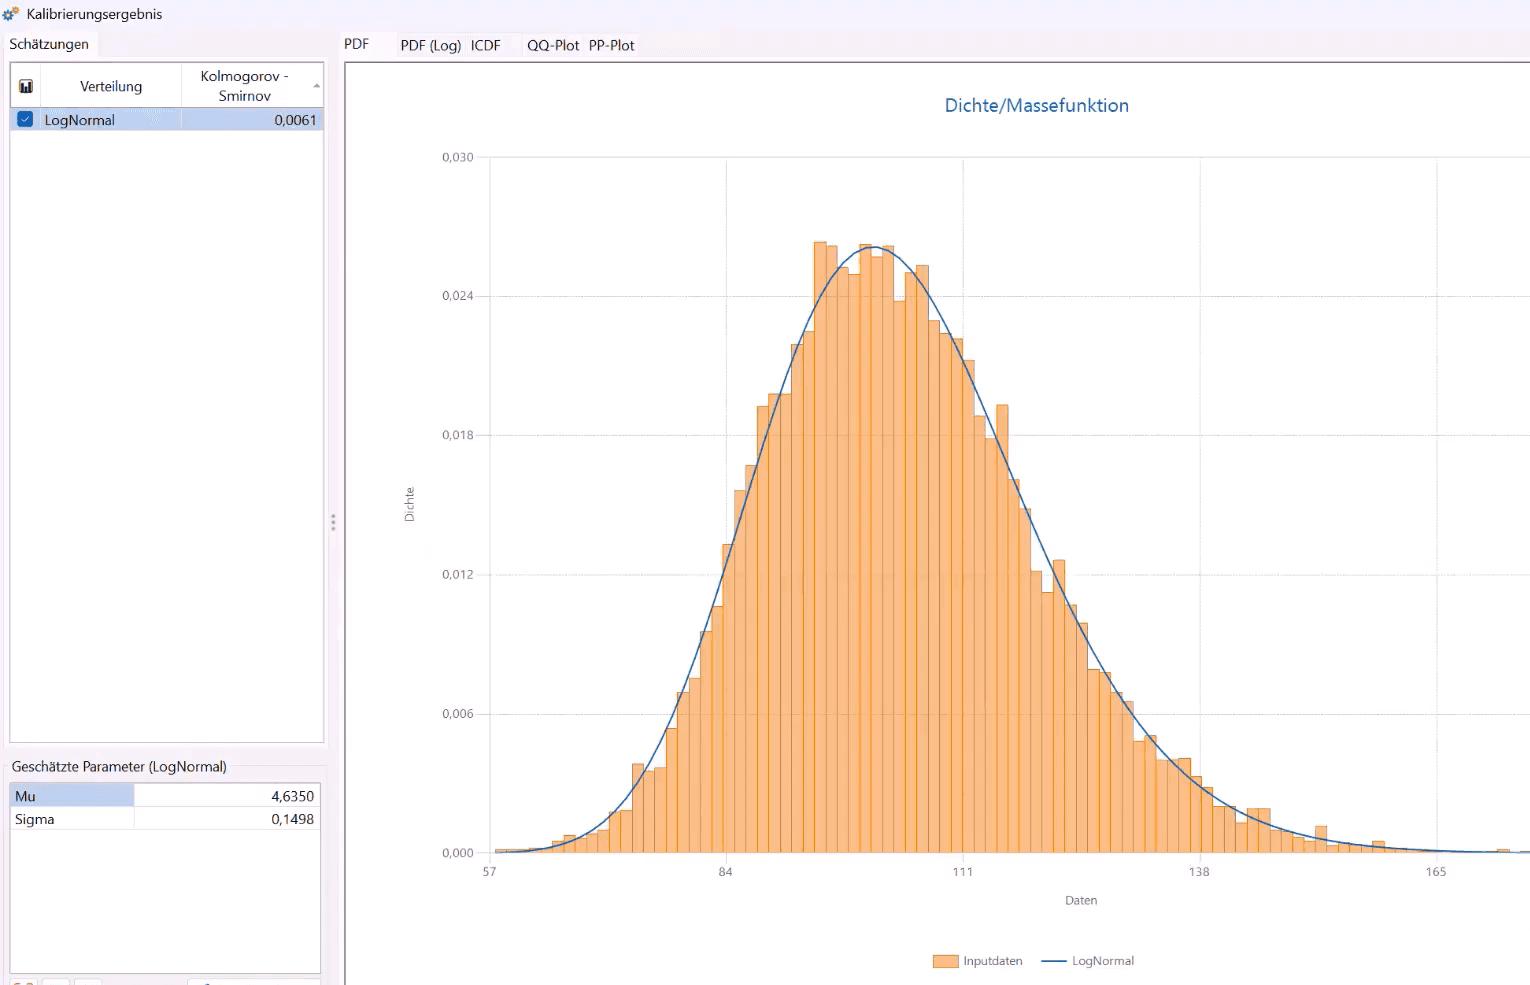 When do I use a lognormal distribution in a Monte Carlo simulation?Definition, properties and limits: when the lognormal distribution correctly describes proportional growth processes and how to parametrise it in Excel.
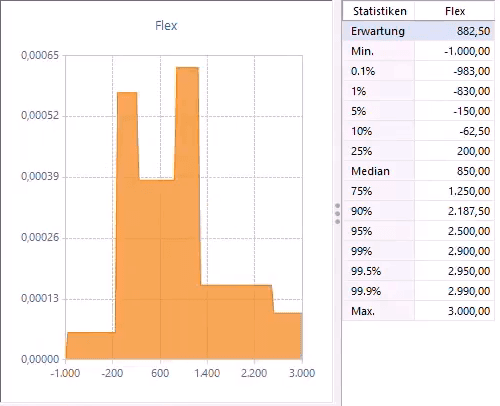 Custom distributions in a Monte Carlo simulation: the Flex distributionCustom distributions: how the Flex distribution is built from values and probabilities and when it fits, from expert estimates to transferring simulation results.
Publications to download.
These papers are hosted on SSRN. A click on the title opens the download page in a new tab.
Monte Carlo simulation
3 publications
Credit risk
9 publications
- Generalized Asset Value Credit Risk Models and Risk Minimality of the Classical Approach
- Strategic Risk and Cost Adjusted Pricing
- Analytic Loss Distributions of Heterogeneous Portfolios In The Asset Value Credit Risk Model
- Estimation of Default Probabilities - Part 1: The Mean Value Model
- Estimation of Default Probabilities - Part 2: Market Factor Based Techniques
- Estimation of Default Probabilities - Part 3: Stochastic Default Probabilities: Credit Risk+
- Estimation of Default Probabilities - Part 4: Default Probabilities Through the Business Cycle: Credit Portfolio View
- Estimation of Default Probabilities - Part 5: Integrated Models - the Credit Risk Evaluation Model
- Credit Risk Evaluation: Modeling - Analysis - Management
Market risk
2 publications
Rating
1 publication
Validation and backtesting
2 publications
Regulation and supervisory law
2 publications
Questions about an article?
If you are interested in an article or have questions about one, please contact us. We are happy to get back to you.